Bathhouses are increasingly looking beyond traditional sauna and bathing experiences, with guided rituals, group programming and new wellness facilities emerging as areas of focus for operators.
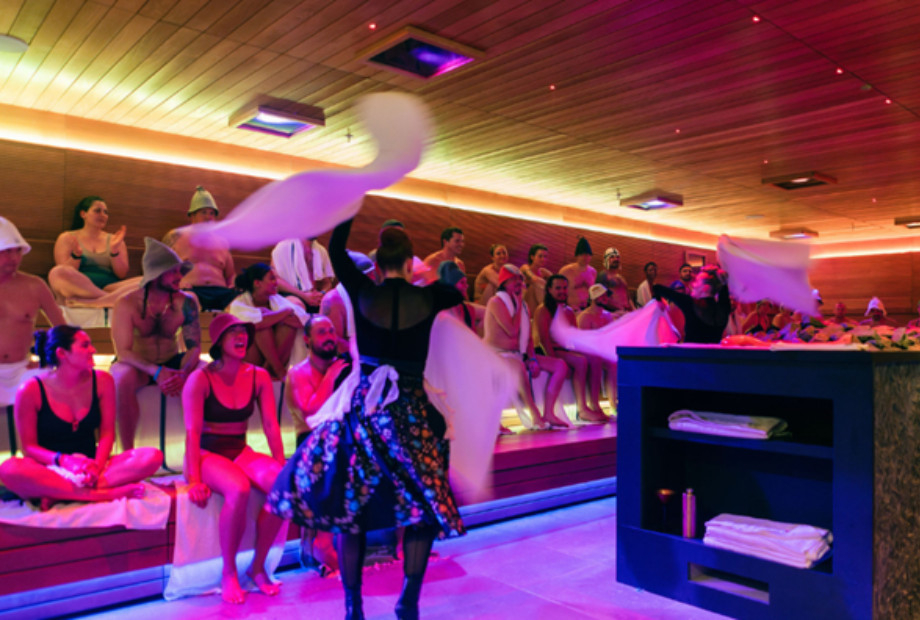
Early findings from the Global Wellness Institute’s 2026 Bathhouse & Thermal Wellness Development Benchmark Survey, based on 47 operator and developer responses, suggest that guided thermal experiences are becoming an important part of the offer. More than three-quarters of respondents either provide or plan to introduce programming such as sauna rituals, breathwork, sound experiences and guided contrast therapy.
Event saunas are also attracting interest, with 21 respondents already operating one and eight planning to introduce one. Alongside these developments, 29 respondents expect to operate multiple locations within three years, indicating expansion ambitions across the sector.
However, growth comes with practical challenges. Almost half of operating businesses that provided development timelines said their projects took two years or longer to progress from concept to opening. Construction costs, permitting and staffing were also highlighted, with more than half of respondents identifying staff recruitment and training as areas prospective owners may underestimate.
The financial findings offer a mixed picture. Of the 37 operating businesses surveyed, 25 reported having reached positive cash flow, with 15 of these achieving it within their first year. Among operating respondents who disclosed monthly revenue, 15 reported gross revenue of at least US$300,000. These figures do not establish profitability, and the survey notes that results vary by business and facility.
Day passes remain the most commonly selected access model, while planned additions such as outdoor areas, warm pools, cold plunges, traditional saunas and food and beverage facilities suggest that operators are exploring ways to broaden the guest experience and diversify their offer.
The survey was conducted through the Global Wellness Institute’s Hydrothermal and Consulting Best Practices Initiatives. The organisation describes the findings as an early, self-reported snapshot, based primarily on US businesses, rather than a representative benchmark of the global market.